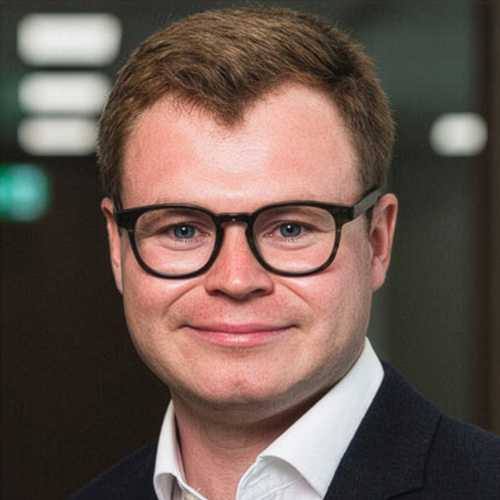
Andrew Wishart
This month, the Alma Spotlight shines on Andrew Wishart, Senior UK Economist at Berenberg. Andrew joined Berenberg as Senior UK Economist in 2024 and was the most accurate sell-side forecaster of the UK economy in 2025 according to The Sunday Times’ annual league table.
We were delighted to co-host a breakfast briefing with Berenberg, where Andrew and Dame Julia Hoggett, CEO of the London Stock Exchange, joined us as guest speakers to share their insights on the UK economy and capital markets. Not content with putting Andrew in the spotlight just once, we managed to persuade him to join us for this month's Q&A, building on some of the themes discussed at the breakfast.
September 2026
Following this week’s discussion with Dame Julia Hoggett, what left you feeling most optimistic about the outlook for UK equity markets – and where do you think the biggest opportunity lies?
Perhaps counter-intuitively, the extent of the challenge itself might be part of the solution. Since the financial crisis the number of companies listed on the London Stock Exchange has more than halved, from over 3,000 to about 1,500 reflecting a dearth of capital flowing into the market. Defined benefit pension schemes have reduced their UK equity allocation from 30% in 2006 to next to nothing as they have switched into gilts to match their liabilities. Our growing Defined Contribution schemes do predominantly invest in equities. But the share of UK listed stocks within that has dropped from 40% to 8% over the past decade.
Because the UK publicly listed universe has shrunk so significantly, even a slight turnaround in investor demand has the potential to provide a sizeable boost. Relatively attractive valuations and the need to diversify away from US-listed hyperscalers alongside policies to nudge domestic investors to put a little more of their money to work at home could reverse the trend.
On the macroeconomic side of the equation, despite the spike in energy prices the underlying performance of the UK economy appears to be improving. The UK has grappled with exceedingly weak productivity growth for almost two decades. After output per head growth of 3% yoy in the 1990s and 2% yoy in the 2000s, it dropped to just 0.5% yoy in the 2010s and softened further in the first half of this decade. Contrary to popular belief, the absence of a substantial improvement in UK living standards since the financial crisis is not because workers are getting less of the proceeds from economic activity. Whereas that argument holds water in the US, where the labour share of income has trended down for the past two decades, in the UK it has been relatively stable, and recently ticked up to its highest level since 2007. Instead, it is very slow productivity growth that explains why GDP-per-capita has disappointed, limiting the tax revenue available to fund public services.
There are sustained signs that the chapter of UK economic history characterised by this productivity puzzle has finally ended. Despite flatlining employment, the UK economy grew by 1.3% yoy in 2025 and is on track to do the same in 2026. Now the biggest increases in the minimum wage and the 2025 jump in payroll taxes are in the rear-view mirror, this growth can feed through to corporate earnings and help attract investment into the UK market.
One of the big themes of the morning was how we get more UK capital behind UK businesses. What do you think needs to change to encourage more domestic savings and pension wealth into UK equities?
Julia is the expert on this one, but I will give it my best shot. Scarred by the jump in prices and mortgage rates after the pandemic, households are saving more than usual but mainly in cash ISAs. Education of the superior long-term returns from equity investment and a rejig of tax incentives to favour investment in UK companies would help. The big pot of domestic capital, though, is our pensions. The stock exchange has run surveys showing that most savers have no idea that so little of their pension is invested in UK companies, so education is part of the solution.
A shift in tax incentives is also critical. When UK investors buy US shares no stamp duty is due, so scrapping it on UK shares would end an active deterrent from investing in UK plc.
We also touched on AI, productivity and the UK’s strength in technology and innovation. How do you see AI affecting UK technology businesses, and what can we do to ensure more of our home-grown innovation is scaled and commercialised here in the UK?
Because the data centre and large-language model markets are highly competitive, the price of AI models and running them should stay low. This will enable the services sector to capture the profits from applying it.
The UK is a world leader in tech innovation and professional services, placing it very well to capture the profits from the application of artificial intelligence to provide services more efficiently. Our research indicates that computer programmers’ adoption of AI accounts for one-third of the increase in output per worker since the end of 2024, the remarkable adaptation of low-pay sectors to the sharp rise in their labour costs another third, and productivity gains in the rest of the economy the remainder.
New companies may be more adept at applying AI than traditional ones, so its important capital markets can provide the funding necessary for these startups to scale up and eventually list in the UK. The policy tweaks I’ve already mentioned will help to do that. But a change in culture is also necessary, to champion these firms rather than focus on how much money their founders have made, and inevitably how we can tax it. We appear to have imported a US view of the country that the top 1% are capturing all the benefits of economic progress. That isn’t the case in the UK, where the labour share of income is much higher and the tax system one of the most progressive in the world.
And lastly, we ask everyone, what is the most interesting thing you've read / watched or listened to recently?
I love Ed Conway’s video explainers of the economic issues in the headlines. He does a brilliant job of laying out an issue in charts and explaining why it matters. His work has been unbelievably helpful in understanding how the Iran war has affected energy supply. Given the selloff in government bonds this week I have to recommend this one.
Please note: The views and opinions expressed in this interview are those of the individual financial professional(s) and do not necessarily reflect the views or opinions of Alma Strategic. These insights are provided for informational purposes only and may not be relevant at the time of reading, as market conditions can change rapidly. The information provided should not be construed as investment advice or a recommendation to buy, sell, or hold any financial product or security. Individuals should conduct their own research and consult with a qualified financial advisor before making any investment decisions. Alma Strategic disclaims any responsibility for the accuracy or completeness of the information provided in this interview.